
The fastest route to a firm-grade deck starts with a vetted downloadable template, either from Corporate Finance Institute or Wall Street Prep, studied alongside real SEC-filed pitchbooks for tone and depth. From there, apply your firm's master slides and lean on a PowerPoint add-in or automation workflow to enforce styling and drop in verified logos. Teams that need speed and consistent branding can cut setup time significantly with a verified automation tool, covered later in this guide.
TL;DR:
- Most templates and real pitchbooks for quick setup are available from sources like CFI, Wall Street Prep, and public SEC filings, but they should be studied rather than copied.
- Standard pitchbook structure includes a title, executive summary, company overview, valuation, transaction strategy, team info, and appendix, with slide counts varying by mandate type.
- Tailoring templates to the specific mandate—sell-side, buy-side, financing, restructuring, or investor decks—is critical to highlight the relevant content and avoid wasted effort.
- Visual formatting rules, such as using appropriate chart types, consistent colors, and clear typography, elevate a deck's professionalism and investment grade appearance.
- Automation tools like Quikturn streamline repetitive tasks such as logo insertion and master slide application, but decks must still pass accessibility and quality checks before finalization.
Table of Contents
- Best places to download templates and real pitch-book examples
- Standard pitch-book structure and slide checklist
- Choosing the right template for your mandate
- Formatting rules that make a deck look investment-grade
- Accessibility and compliance in investor-facing decks
- Speeding template customization with the right workflow
- How the Quikturn Team thinks about narrative and clarity
- How Quikturn speeds template work and where to try it
- Sources
- FAQ
Best places to download templates and real pitch-book examples
Most analysts waste hours hunting for a starting file that actually resembles what a managing director expects to see. A handful of sources cover nearly every need, from generic frameworks to real deal artifacts.
Corporate Finance Institute publishes a free downloadable pitchbook template that follows the standard five-section structure: company overview, industry overview, valuation, transaction opportunities, and team overview. It works well as a starter file because the section order matches what most bulge bracket and boutique decks follow, so you spend your time on content instead of rebuilding a table of contents from scratch.
Wall Street Prep's pitchbook guide goes a step further, pairing structured outlines with explanations of what belongs on each slide, including guidance on building valuation and comps sections. Mergers & Inquisitions covers similar ground with commentary aimed at breaking into the industry, useful if you are new to the format and need the reasoning behind each slide, not just the layout.
For realism, nothing beats studying actual deals. Collections like Alexander Jarvis's presentation archive and 10xEBITDA host dozens of real bank presentations across advisory firms, which help you calibrate slide depth, language, and how much detail a live pitch actually carries versus a template's placeholder text.
SEC EDGAR takes this further still. Public filings sometimes include pitchbook exhibits attached to proxy materials, giving you an authoritative look at real slide language, redaction patterns, and appendix depth that banks provide in actual public transactions.
A few practical notes on using these sources:
- Prefer PPTX over PDF when you plan to edit content directly, since PDF templates require rebuilding charts and tables from scratch.
- Use generic templates like CFI's for structure and speed, but validate tone and slide density against a real SEC-filed example before finalizing a client-facing deck.
- Treat presentation collections as study material, not copy sources: match the pacing and claim density, not the specific company language.
- Check licensing notes on any third-party template before distributing it externally, since some training-site templates restrict commercial redistribution.
Standard pitch-book structure and slide checklist
Every mandate type has its own emphasis, but the underlying skeleton rarely changes. Knowing this structure lets you evaluate any downloaded template in minutes and spot what is missing before you start filling slides.
- Title and table of contents. One slide establishing the mandate, date, and confidentiality language, followed by a navigable agenda.
- Executive summary. A single headline claim (the recommended action or valuation range) supported by three bullets, no more, that a reader could act on without seeing another slide.
- Company and market overview. Business description, historical financials, and a market sizing section that frames why the transaction makes sense now.
- Valuation and comparable companies. A comparable company set, a multiples table, and a football field chart summarizing the valuation range across methodologies.
- Transaction strategy and opportunities. The specific rationale, whether that is buyer universe for a sale process or synergy logic for an acquisition.
- Team overview. Deal team bios and relevant transaction experience, typically one slide, sometimes folded into the appendix on shorter decks.
- Appendix. Detailed model outputs, expanded comps, legal disclosures, and source citations that support but do not clutter the main narrative.
The CFI template maps directly onto this order, which is part of why it works as a starting point regardless of mandate. Wall Street Prep's guide breaks the valuation section down further, showing how the comps table and football field should relate: the table gives the analytical detail, and the football field compresses it into a visual range a client can scan in seconds.
Slide counts vary by mandate and audience, but a full sell-side pitchbook commonly runs longer than an internal investment committee deck, since the latter assumes more shared context. What matters more than total count is appendix discipline. A one-page appendix checklist helps here:
- Full detailed model output (DCF, LBO, or merger model as relevant).
- Extended comparable company set beyond what fits on the main slide.
- Legal disclosures and confidentiality language.
- Source citations for every market figure and multiple used in the main deck.
Cutting a slide from the main deck does not mean losing the content: move it to the appendix, and keep only the conclusion visible where the client is actually looking. A common failure mode is letting appendix material bleed into the main narrative because an analyst could not decide what to cut. The fix is almost always to ask whether a slide supports the headline claim in the executive summary. If it does not, it belongs in the back.
Choosing the right template for your mandate
A generic pitchbook template gets you most of the way there, but the mandate type determines which sections need the most weight and which can shrink or disappear entirely.
- Sell-side mandates lean heavily on buyer universe analysis, precedent transaction comparisons, valuation ranges, and a clear process timeline, since the client is deciding who to run a process with and how long it will take.
- Buy-side or bidder decks shift the emphasis to valuation sensitivity tables, synergy scenarios, integration planning notes, and the financing assumptions behind the offer.
- Financing and credit decks need covenant schedules, multi-year cash-flow projections, and stress-tested scenario tables, since the audience is evaluating downside risk more than growth story.
- Restructuring and process update decks center on a timeline, creditor mapping, a menu of restructuring options, and a cash runway slide that anchors urgency.
- Investor and board decks run shorter and metrics-first, front-loading the numbers that matter and pushing supporting financials into an appendix the board can consult if questions arise.
Trying to force a sell-side template onto a restructuring mandate, or vice versa, wastes more time than starting from a blank outline, because the slide priorities and the supporting data are fundamentally different. Match the template family to the mandate before you touch content. For financing decks specifically, understanding how valuation assumptions feed lender decisions helps frame the covenant and cash-flow sections correctly, a connection Fordham Capital's writeup on startup valuation and loan eligibility lays out from the lender's side.
Formatting rules that make a deck look investment-grade

Content quality gets a deck in the room. Formatting discipline is what makes it look like it belongs there.
Chart selection is the most common failure point. Use line charts for trends over time, clustered bars for category comparisons, and waterfall charts for step changes like a bridge from EBITDA to enterprise value. Avoid pie charts for anything time-based: they compress a trend into a single, hard-to-compare snapshot.
- Assign one primary brand color to the focal data series and use neutral gray for comparison series, so the reader's eye goes to the number that matters first.
- Cap the deck's palette at four brand colors total, including any accent used for callouts or highlights.
- Align decimals in every comps and data table, use small-caps or bolded headers, and apply alternating row shading so a table with fifteen rows stays scannable.
- Build the football field graphic as horizontal bars, one per valuation methodology, with the current price or offer marked as a vertical reference line across all bars.
- Use a three-level typography hierarchy: headline text at 28 to 32 point, callout text at 20 to 24 point, and body text at 14 to 16 point, set on a 12-column grid so every slide element lines up across the deck.
Design practitioners who work specifically on financial presentations recommend building master slides around this grid so analysts only paste data into predefined table styles rather than rebuilding alignment and shading slide by slide. That single habit removes most of the formatting inconsistency that shows up in decks assembled by multiple analysts under deadline pressure.
Before a deck goes out, run a final quality pass:
- Confirm the logo, date, and footer source line are identical across every slide.
- Check that every slide title states a single headline claim, not a topic label.
- Verify footnotes exist for every assumption driving a valuation or projection figure.
- Scan for orphaned placeholder text left over from the original template.
Pro Tip: Keep one master slide per chart type (comps table, football field, waterfall) locked in your firm template so analysts paste data instead of rebuilding formatting from scratch every time.
Accessibility and compliance in investor-facing decks
Investor and public-facing decks increasingly need to work for readers using screen readers or assistive technology, not just for the room they are presented in. This matters most when a deck becomes a filed exhibit or gets distributed as a PDF attachment to a broader audience than the original pitch meeting.
A handful of steps cover most of the requirement:
- Use PowerPoint's built-in Table tool rather than pasted images so screen readers can parse row and column structure.
- Add descriptive slide titles and structural tags so navigation tools can jump between sections correctly.
- Supply alt text for every chart, logo, and image, describing the data or content rather than just naming the file.
- Maintain at least 4.5 to 1 color contrast between text and background, particularly for footnotes and axis labels.
- Avoid embedding text inside images or SmartArt graphics, since that text becomes invisible to assistive tools entirely.
When exporting to PDF, structural tags carry over only if the source PowerPoint file was tagged correctly, which is why fixing accessibility at the slide level matters more than trying to patch a PDF after the fact. The CMS Section 508 PowerPoint guide walks through each of these steps in detail, including how PowerPoint's accessibility checker flags missing alt text and untagged tables before export. Pairing every chart with a corresponding data table, beyond helping accessibility, also gives auditors and legal reviewers a numeric record that does not depend on interpreting a visual.
Speeding template customization with the right workflow
The slowest parts of building a pitchbook are rarely the analysis itself. They are the repetitive production tasks: finding a clean company logo, applying master slide formatting across forty slides, and restyling a comps table for the third time because the client changed the peer set.
Each of these has a fix. Logo lookup and insertion can run through a verified database instead of a manual image search, which also avoids the inconsistent resolution and background issues that come from grabbing logos off a company website. Master slide updates apply instantly when a firm template is locked at the platform level rather than copied slide by slide. Table styling stays consistent when comps tables are built once as a reusable component rather than reformatted for every new deal.
Quikturn's PowerPoint add-in and API address these specific bottlenecks for finance teams: a verified database of over 17 million company logos removes the manual search step, rapid deck generation drafts market maps and company slides directly in native PowerPoint format, and the add-in integrates into existing firm templates rather than replacing them. That combination targets the exact production drag most analysts hit when a deck's content is done but the formatting still needs an hour of manual cleanup.
- Insert logos and company details automatically at the company overview and buyer universe stages rather than searching manually.
- Apply the firm's master slide template once, at the platform level, so every generated slide inherits consistent styling.
- Run automation output through the same QA and Section 508 checklist used for manually built decks, since automation speeds production but does not replace review.
Pro Tip: Bring an automation tool into your workflow at the drafting stage, not the final review stage, so your QA checklist still catches formatting and accessibility issues before a deck goes to a client.
How the Quikturn Team thinks about narrative and clarity
A pitchbook succeeds or fails on whether it makes one argument clearly, not on how much analysis it contains. We push every deck toward a single narrative thread: one recommendation, one valuation range, one reason the transaction makes sense now. Everything else earns its place only if it supports that thread.
The executive summary is the hardest slide to get right precisely because it has to compress the entire argument into a headline claim and three bullets. We treat the appendix as a release valve, not a dumping ground: detail that would slow down the main narrative moves there, but only if it is not the fact carrying the recommendation. The discipline of cutting a well-built slide because it does not serve the central claim is, in practice, the difference between a pitchbook that lands and one that reads like a research report.
— Quikturn Team
How Quikturn speeds template work and where to try it
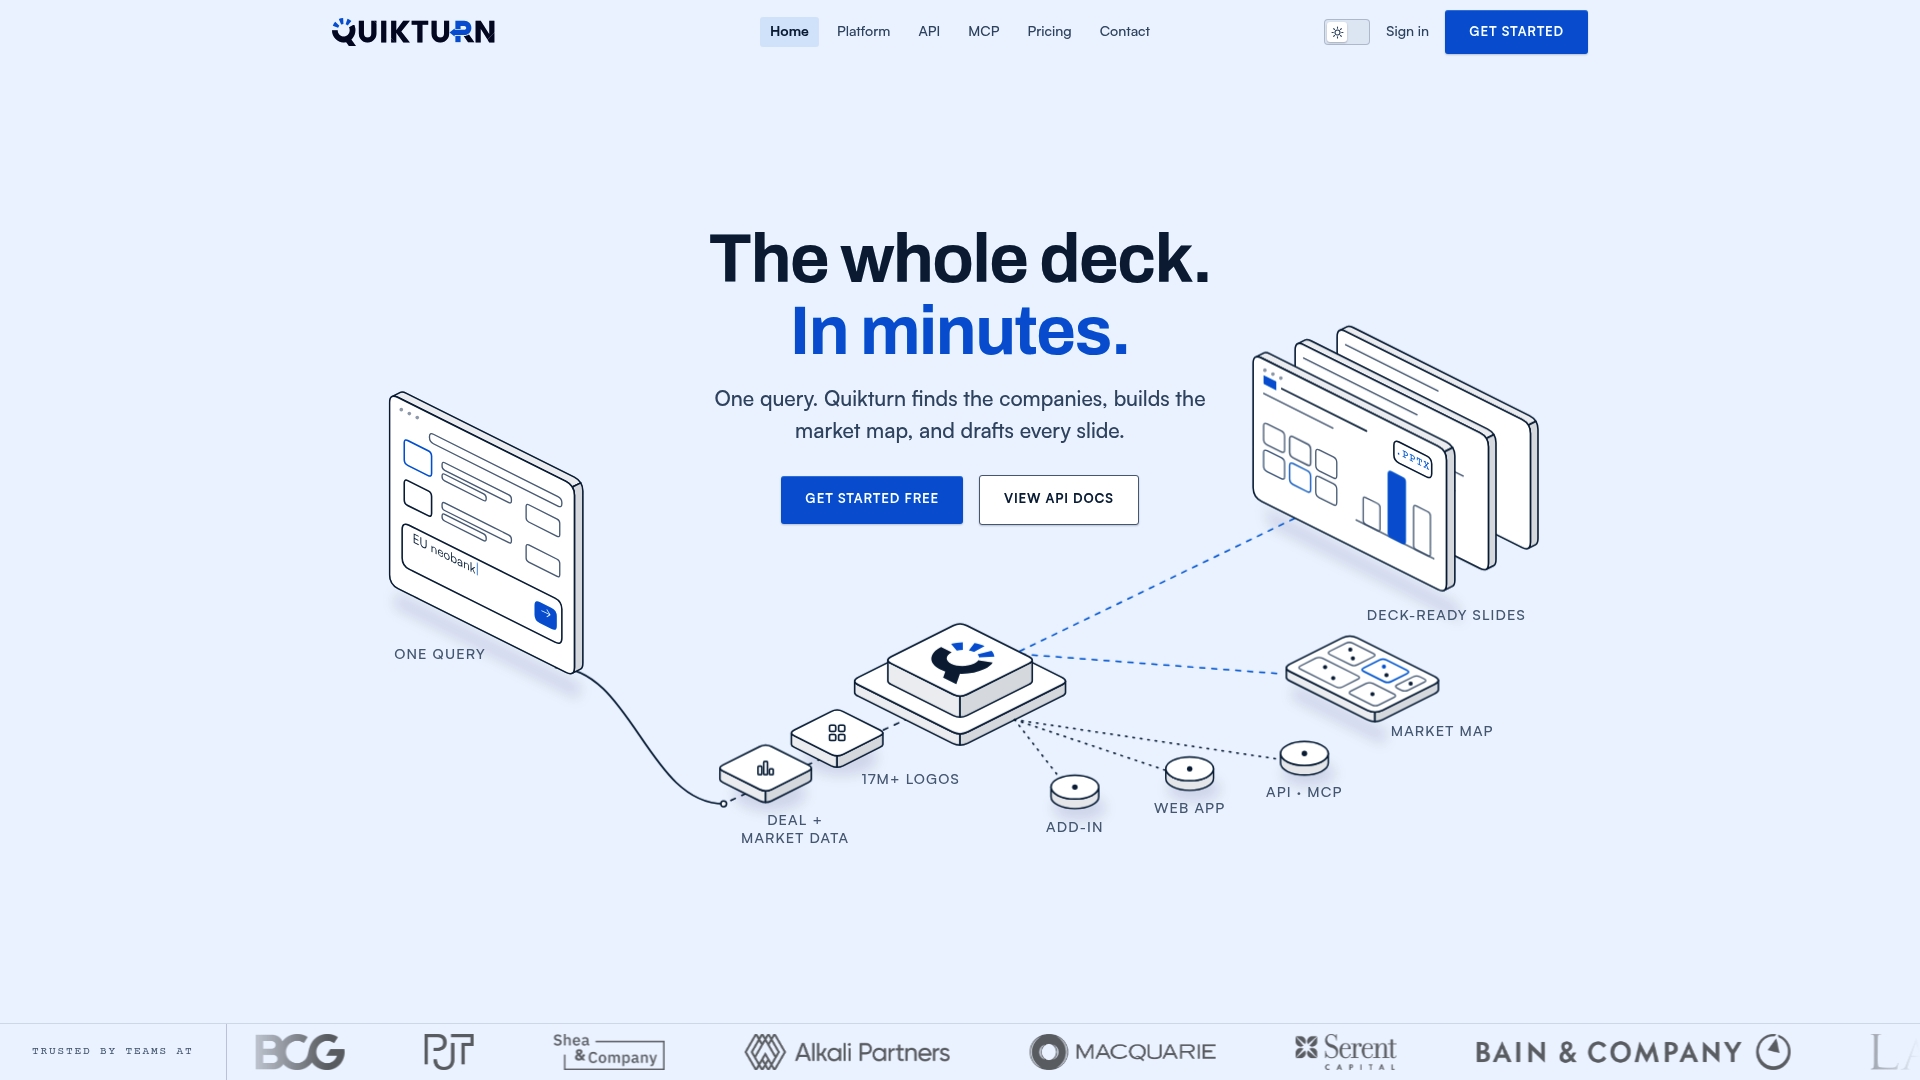
Building a compliant, on-brand pitchbook still takes too long when every logo needs a manual search and every master slide update means touching forty individual slides by hand. Quikturn removes that drag at the exact points covered above: logo insertion pulls from a verified database of over 17 million entries, master slide styling applies automatically once configured, and slide drafting for company overviews and market maps happens directly inside PowerPoint through the add-in or via API for teams that want it built into their own tools.
The Platform Free plan provides analysts a way to test logo search and insertion before committing to a paid tier, while Platform Pro offers higher usage options for teams. Investment banking teams evaluating fit can review the dedicated solutions page or head straight to get started to set up an account. Whatever pace you automate at, keep running the same Section 508 and QA checks on generated slides that you would run on any manually built deck.
Sources
Start with the CFI pitchbook template for a free, structurally sound PPT covering the five standard sections. Cross-reference it against Wall Street Prep's pitchbook guide for section-by-section explanations, then study real decks through Alexander Jarvis's collection to calibrate tone and depth.
- Investment Banking Pitchbook Template - Download Free PPT File
- Real Investment Banking M&A Presentations
- SEC filing exhibit (example pitchbook)
- PowerPoint 508 accessibility guide (CMS/HHS)
- Investment Banking Pitchbook | Format + Examples
FAQ
Is a 3.6 GPA bad for investment banking recruiting?
A competitive GPA for investment banking recruiting is generally around a B+ to A- level. Strong internship experience, networking, and technical interview performance typically matter as much as the exact decimal GPA threshold.
Who are the largest firms in investment banking?
The largest investment banks by global market presence typically include Goldman Sachs, JPMorgan, Morgan Stanley, and Bank of America, often grouped informally as leading bulge bracket firms. Rankings shift by deal volume and region, so "largest" depends on the specific league table and year being referenced.
Do investment bankers still rely on Excel for financial modeling?
Yes, Excel remains the primary tool for financial modeling in investment banking, including for the DCF, comps, and LBO outputs that feed directly into pitchbook valuation slides. Newer tools handle presentation formatting and data lookup, but the modeling layer itself still runs through Excel at most firms.
Who typically earns more, private equity or investment banking?
Private equity professionals often earn more than investment bankers at comparable seniority levels, largely due to carried interest and profit-sharing structures unavailable in banking roles. Base salaries between the two are often closer than total compensation suggests, since bonus and carry structures drive most of the difference.